
Construction Equipment Market
2025-10-31
Healthcare
abhijit patil
Description
North America Electric Bus Market Size
The North America electric bus market size was valued at USD 1029.90 million in 2024 and is projected to reach from USD 1164.71 million in 2025 to USD 3116.11 million by 2033, growing at a CAGR of 13.09% during the forecast period (2025-2033).
E-buses use electric motors instead of ICE engines. E-bus motors are battery-powered. They're cheaper than gas/diesel buses. Demand for fuel-efficient, high-performance, low-emission buses, government vehicle emission restrictions, and lowering battery prices drive the market.
Market Summary
| Market Metric | Details & Data (2024-2033) |
|---|---|
| 2024 Market Valuation | USD 1029.90 Million |
| Estimated 2025 Value | USD 1164.71 Million |
| Projected 2033 Value | USD 3116.11 Million |
| CAGR (2025-2033) | 13.09% |
| Key Market Players | BYD Auto, PROTERRA INC, AB VOLVO, Blue Bird Corporation, Gillig |

to Get Detailed Insights.
Market Growth Factor
Growing Demand for Energy-Saving and Emission-Free Mass Transit Options
Transportation is a major source of GHG emissions. Due to the high cost of developing electric buses and coaches and related parts like batteries and monitoring systems, electric bus manufacturers are severely constrained by urban and regional air pollution, making up about a quarter of all energy-related greenhouse gas (GHG) emissions, according to UNEP. According to the EPA, buses also emitted 1.1% of the transportation sector's GHGs in 2019. 29% of ozone-depleting pollutants come from automobile exhaust. Many governments have implemented electric bus schemes to increase urban public transportation sustainability and fuel economy. The Federal Transit Administration (FTA) of the U.S. Department of Transportation announced USD 130 million for Low or No Emissions in June 2020.
North America Electric Bus Market Restraint
Limited Availability of Charging Infrastructure
Electric bus charging infrastructure can limit utilization. A large-scale charging infrastructure network requires significant investment and planning. Many places lack fast-charging stations for electric buses. 65% of transit agencies surveyed by the U.S. National Renewable Energy Laboratory (NREL) said the lack of charging infrastructure or its incompatibility was a major impediment to electric bus adoption. This constraint might cause range anxiety and operational issues for electric bus fleets.
Market Opportunity
Advancements in Battery Technology
Battery technology is expanding electric bus options. Battery energy density, charging speed, and durability improve electric bus range and performance. Electric buses will become more viable as battery costs drop. California-based Proterra pioneered electric bus battery technology. Proterra EnergyTM is their high-performance battery system. These battery solutions have an industry-leading energy density, allowing electric buses to travel farther per charge. Solid-state batteries could transform electric bus capabilities in the future.
Regional Analysis
The North American electric bus market is analyzed across the U.S., Canada, and Mexico. The U.S. dominated the market and is expected to grow at a CAGR of 13.27% during the forecast period.
North America is predicted to experience definite expansion. The U.S. is expected to continue to grow steadily in this area. The industry is projected to grow in the upcoming years due to the nation's strict emission regulations. North American demand for electric buses is rising due to the infrastructure's expansion, including installing more stations and charging stations. Government initiatives to enhance public transportation while lowering pollution have allowed electric buses to be developed. Governments are also ready to spend money and lower automobile levies. Additionally, the growing emphasis on reducing carbon emissions and boosting public sector revenue has sparked the expansion of the electric bus market. They are improving transportation and greenhouse gas reduction targets.
Propulsion Type Analysis
Propulsion Type further segments the market into BEV, PHEV, and FCEV. BEV segment dominates the market and is expected to grow at a CAGR of 13.14% during the forecast period.
Component Analysis
Component further segments the market into Motor, Battery, Fuel Cell Stack, Battery Management System, Battery Cooling System, and E.V. Connectors. Battery dominated the market and is expected to register a CAGR of 13.56% over the forecast period.
Consumer Segment further segments the market into Fleet Operators, Government. The Fleet Operator segment dominates the market and is expected to grow at a CAGR of 12.67% during the forecast period.
Length of Bus Analysis
The market is further segmented by Length Of The Bus into Less Than 9m, 9-14m, and Above 14m. The 9-14m segment dominates the market and is expected to grow at a CAGR of 13.29% during the forecast period.
Application Analysis
The market is further segmented by application into Intercity, Intracity. Intracity dominated the market and is expected to register a CAGR of 13.38% over the forecast period.
Vehicle Range Analysis
The market is further segmented by Vehicle Range into Less Than 200 Miles, Above Miles. The less than 200 miles segment dominates the market and is expected to grow at a CAGR of 13.40% during the forecast period.
Battery Capacity Analysis
Battery Capacity further segments the market into up to 400kwh and above 400kwh. Up To 400 kWh segment dominates the market and is expected to grow at a CAGR of 12.90% during the forecast period.
Power Input Analysis
The market is further segmented by Power Input into Up to 250kw, Above 250kw. Up to 250kw dominated the market and is expected to register a CAGR of 12.89% over the forecast period.
Battery Type Analysis
The market is further segmented by Battery type into Lithium-Nickel-Manganese-Cobalt-Oxide, Lithium-Iron-Phosphate. The lithium-Iron-Phosphate segment dominates the market and is expected to grow at a CAGR of 13.36% during the forecast period.
List of Key and Emerging Players in North America Electric Bus Market
- BYD Auto
- PROTERRA INC
- AB VOLVO
- Blue Bird Corporation
- Gillig
- The Lion Electric Company
- Tata Motors
- JBM Auto Limited (JBM Group)
- Scania
- Škoda Transportation
- NFI Group
Recent Developments
- May 2023- Volvo Group contracts long-term renewable electricity from Vattenfall.
- May 2023- Lion Electric Company launched the Lion5, an all-electric Class 5 vehicle powered by LionBattery packs, its 800V battery packs.
Report Scope
| Report Metric | Details |
|---|---|
| Market Size in 2024 | USD 1029.90 Million |
| Market Size in 2025 | USD 1164.71 Million |
| Market Size in 2033 | USD 3116.11 Million |
| CAGR | 13.09% (2025-2033) |
| Base Year for Estimation | 2024 |
| Historical Data | 2021-2023 |
| Forecast Period | 2025-2033 |
| Report Coverage | Revenue Forecast, Competitive Landscape, Growth Factors, Environment & Regulatory Landscape and Trends |
| Segments Covered | By Propulsion Type, By Power Output, Battery Type, By Length Of Bus, By Seating Capacity, By Level of Autonomy, By Range, By Application, By Battery Capacity, By Component |
abhijit patil
Abhijeet Patil is a Research Associate with 3+ years of experience in Automation & Process Control and Automotive & Transportation sectors. He specializes in evaluating industry automation trends, mobility innovations, and supply chain shifts. Abhijeet’s data-driven research aids clients in adapting to technological disruptions and market transformations.
Our Research Methodology
"Insight without rigor is just noise."
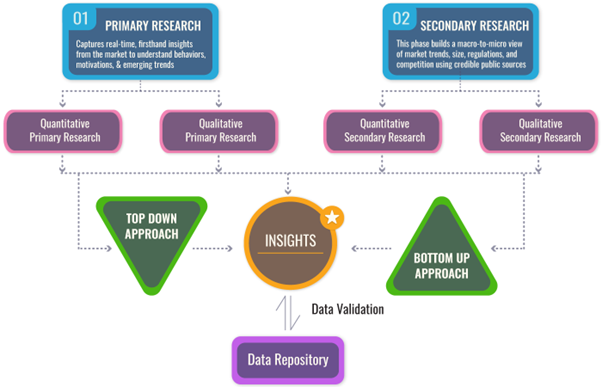
We follow a comprehensive, multi-phase research framework designed to deliver accurate, strategic, and decision-ready intelligence. Our process integrates primary and secondary research , both quantitative and qualitative , along with dual modeling techniques ( top-down and bottom-up) and a final layer of validation through our proprietary in-house repository.
PRIMARY RESEARCH
Primary research captures real-time, firsthand insights from the market to understand behaviors, motivations, and emerging trends.
1. Quantitative Primary Research
Objective: Generate statistically significant data directly from market participants.
Approaches:- Structured surveys with customers, distributors, and field agents
- Mobile-based data collection for point-of-sale audits and usage behavior
- Phone-based interviews (CATI) for market sizing and product feedback
- Online polling around industry events and digital campaigns
- Purchase frequency by customer type
- Channel performance across geographies
- Feature demand by application or demographic
2. Qualitative Primary Research
Objective: Explore decision-making drivers, pain points, and market readiness.
Approaches:- In-depth interviews (IDIs) with executives, product managers, and key decision-makers
- Focus groups among end users and early adopters
- Site visits and observational research for consumer products
- Informal field-level discussions for regional and cultural nuances
SECONDARY RESEARCH
This phase helps establish a macro-to-micro understanding of market trends, size, regulation, and competitive dynamics, sourced from credible and public domain information.
1. Quantitative Secondary Research
Objective: Model market value and segment-level forecasts based on published data.
Sources include:- Financial reports and investor summaries
- Government trade data, customs records, and regulatory statistics
- Industry association publications and economic databases
- Channel performance and pricing data from marketplace listings
- Revenue splits, pricing trends, and CAGR estimates
- Supply-side capacity and volume tracking
- Investment analysis and funding benchmarks
2. Qualitative Secondary Research
Objective: Capture strategic direction, innovation signals, and behavioral trends.
Sources include:- Company announcements, roadmaps, and product pipelines
- Publicly available whitepapers, conference abstracts, and academic research
- Regulatory body publications and policy briefs
- Social and media sentiment scanning for early-stage shifts
- Strategic shifts in market positioning
- Unmet needs and white spaces
- Regulatory triggers and compliance impact
DUAL MODELING: TOP-DOWN + BOTTOM-UP
To ensure robust market estimation, we apply two complementary sizing approaches:
Top-Down Modeling:- Start with broader industry value (e.g., global or regional TAM)
- Apply filters by segment, geography, end-user, or use case
- Adjust with primary insights and validation benchmarks
- Ideal for investor-grade market scans and opportunity mapping
- Aggregate from the ground up using sales volumes, pricing, and unit economics
- Use internal modeling templates aligned with stakeholder data
- Incorporate distributor-level or region-specific inputs
- Most accurate for emerging segments and granular sub-markets
DATA VALIDATION: IN-HOUSE REPOSITORY
We close the loop with proprietary data intelligence built from ongoing projects, industry monitoring, and historical benchmarking. This repository includes:
- Multi-sector market and pricing models
- Key trendlines from past interviews and forecasts
- Benchmarked adoption rates, churn patterns, and ROI indicators
- Industry-specific deviation flags and cross-check logic
- Catches inconsistencies early
- Aligns projections across studies
- Enables consistent, high-trust deliverables